Monday, May 28, 2007

More on the TD Ameritrade Switchover

I had a couple of other notes about the switchover of TD Waterhouse clients to the new TD Ameritrade website. I needed to change login information for Microsoft Money, Quicken, and my online account aggregation sites (which are powered by Yodlee).

MS Money and Quicken never did display the correct account balance information for TD Waterhouse, so this is nothing new. On the other hand, I also use MSN Money and a Smith Barney account (powered by Yodlee). In the case of MSN Money, its seems to double count my cash balance, listing cash as both an "unknown" security and then again in the cash section. Smith Barney drops the cash amount altogether, thus under reporting my account balances. Does anybody else experience these issues with account aggregation?

As far as MS Money and Quicken (I use both) are concerned, there were a bunch of extraneous transactions caused by the changeover. On the TD Ameritrade website, these are listed as "TRANSFER OF SECURITY OR OPTION IN" and are dated 05/14/2007. In MS Money, these are listed as a series of "Remove Shares" and "Add Shares" transactions. Because the number of shares added and removed are equal, these transactions cancel out. But I had to mark both transactions as void to retain my original purchase dates and cost basis information.

Another big change at TD Ameritrade is the addition of a gain/loss tracking tool provided by GainsKeeper. I have used GainsKeeper before, and I believe that it can be very helpful to keep track of the cost basis of investments. However, the first obstacle for me is that GainsKeeper doesn't have any cost basis information for investments I bought before 2003 or so. I had to go through a process known as "baselining" to tell the online tool what I originally paid for my stocks and mutual funds. For the most part, this process is straightforward if you have your cost basis handy. However, if a stock or fund has undergone a stock split, spinoff, or merger, it can get very confusing. For example, I have 0.001 shares of T ROWE PRICE EQUITY INDEX (symbol: PREIX) that I don't know the cost basis for! This was originally the TD Waterhouse 500 Index that got merged into T. Rowe Price. When I was finally done updating and correcting the cost basis, I noticed that these updates don't seem to be reflected on the "Balances & Positions" page. There must be two different sources for cost basis data, which can be confusing.

In addition to the Streamer Suite of online tools, the new TD Ameritrade website also includes a couple of tools that you can download (and install on your computer). These are StrategyDesk and Advanced Analyzer. I have experimented a little with StrategyDesk which is designed to help you find a successful trading strategy. I have not installed Advanced Analyzer yet.

Lastly, for my money market fund which is officially called the "TDAM Money Market Portfolio – Investor Class," the symbol that TD Ameritrade uses changed from CMFMZ to 9ZZZTD109. I'm not sure about the reason for this change.

PF Stock

Tuesday, May 22, 2007

NetBank's Demise

PFStock has helped to chronicle the ongoing demise of the online bank NetBank. In my first posting (Sayonara NetBank) dated September 20, 2006, I stated that I was beginning the process of "evacuating my money" from NetBank. In subsequent posts on PFStock, I cited deteriorating financial conditions at NetBank as my prime reasons for closing out my account. Although I conceded that NetBank was not likely to be forced into bankruptcy, I felt that it would be a hassle for depositors to get their funds back from the FDIC.

In my more recent post, on April 15th (NetBank Revisited), I advised any of my readers that still owned shares of NetBank (Nasdaq: NTBK) to get out, even though the NTBK shares then trading at $1.74 per share seemed cheap at the time. Quoting myself:

For NTBK shareholders, I think that there are better investments out there. Taking a loss may be a difficult thing, but so is watching your remaining investment dwindle to practically nothing.


Yesterday (May 21st), the other shoe dropped. NetBank announced that it is selling a substantial portion of what remaining assets it has to privately held EverBank. Here are a couple of statements from the NTBK press release:

The company has been under extreme financial pressure for more than a year due to a difficult mortgage origination market, a flat yield curve environment and other factors. These pressures have resulted in large operating losses that have significantly reduced the company's capital position and prompted heightened regulatory oversight.

And:

Regulators have been increasingly concerned about the bank's capital and earnings trends and advised management to find an alternative immediately that covered all of the bank's deposit obligations.


Doesn't this seem to imply that the aforementioned "regulators" forced NetBank to essentially liquidate its remaining assets in order to protect depositors' money? And the NTBK stock price has reacted very negatively to these developments. On Friday, May 18th, NTBK closed at 1.75, and it closed Monday at 0.59 (a stunning 66% one-day decline).

So, what is left of NetBank? According to NetBank CEO, Steven F. Herbert, "Our remaining businesses will include our mortgage servicing operation, along with our retail prime mortgage franchise, Market Street Mortgage." My interpretation is that there won't be anything left of the online banking operation, after EverBank takes its share. So substantially I can say that as you and I know it, the online bank, NetBank is no more!

NOTE: On May 12th PFStock received an anonymous comment that said, "Stay tuned for more on NetBank. There might even be some big news this coming week." (See Obsession Tagged.) I know for a fact that NetBank employees regularly read this blog, but I was not able to ascertain the identity of the commenter. Nevertheless, it is clear now that this event is what the anonymous reader was referring to.

I don't know if there is really much more to say about the NetBank situation, other than, "I told you so".

For further reading:
NetBank Revisited
The Decline and Fall of Internet-only Banks
Unprofitable and Unstable, NetBank Ousts its CEO
More on NetBank
Sayonara NetBank

PF Stock

Friday, May 18, 2007

TD Ameritrade Update and a Warning

PFStock has helped to chronicle the travails of Ameritrade as it swallows up the brokerage formerly known as Waterhouse Securities. This past week, the assimilation was completed. For former Waterhouse customers, we have been switched to Ameritrade's new web site. I had previously described this upgraded web site in the post: Ameritrade's Unimpressive Site Upgrade.

For long-time Waterhouse customers, like myself, this is a significant changeover. Notices have been posted on the TD Ameritrade on the website indicating that the brokerage firm is experienced a very high volume of calls to customer service. Presumably, this is due to a great many former Waterhouse customers who are, at best, confused by the new web site.

Before I continue with what is becoming a long post, I will now issue the warning that is mentioned in the title of this post. Here is my warning about he the new website:

If you formerly received paper statements from Waterhouse, the new TD Ameritrade will now charge you $2 per month for paper statements, unless you are an Apex client.

This notice was incorporated in the many reams of paper that TD Ameritrade sent out to its clients. In case you missed the change, I am letting you know now.

From my perspective, I am finally an Apex client at TD Ameritrade. However, by the arcane system that TD Ameritrade uses, my DW is not considered an Apex client. Although we (as a household) have more than double the required assets for Apex access, there is less than $100,000 in my wife's combined accounts, so they don't count her as Apex.

TD Ameritrade has been touting such features as Trade Triggers, which the new site has. They also now offer conditional orders. I use Standard and Poors (S&P) stock reports extensively for my personal research. And TD Ameritrade allows customers to access S&P reports for most companies. Typically, these S&P stock reports are 8 pages long. There are some other improvements to the site including the very good Streamer Suite of online investment tools. There is also the new Command Center 2.0, and StrategyDesk.

However on the downside, the new TD Ameritrade website does not give access to IPOs. And currently, customers cannot access the cost basis information for their investments. My general opinion is that customer service at TD Ameritrade is lacking unless you are able to make friends with a representative at a local branch office. In that case, you can call your representative with your issues, and have them do battle with their own customer service department.

As I described in my previous post, the new stock screener is still hard to use. I had trouble figuring out how to use the Ameritrade stock screener, so I've abandoned it and will instead use the free stock screener from Yahoo Finance. And I am still receiving spam at my Ameritrade Email address. In a previous post on the topic, I mentioned how I use a unique Email address for my Ameritrade account. This is accomplished through Yahoo's "AddressGuard" feature.

Lastly, I want to remind readers that better choices exist for the TD Ameritrade's money market (cash sweep) account. Typically, these fund options pay 4-5% APY while if you let let TD Ameritrade assign you to the default FDIC-insured sweep account, you will earn as little as 0.1% interest on your money.

For information on money market (cash sweep) funds, see this post: Ameritrade's "Hidden" Cash Sweep Account.

For information about enhanced cash funds which pay about 5.4% APY, see this post: Money Market Fund Options for TD Ameritrade. By the way, the symbol for this fund is RYPQX and it is offered through The Reserve.

PF Stock

Saturday, May 12, 2007

Blogger Beta Strikes PFStock

I've been resisting the move to the new Blogger Beta for as long as I could. However last month, Google automatically changed my blog over to Blogger Beta. Now, some blog elements no longer display correctly, especially when using Microsoft Internet Explorer 7 (IE7). Most notably, I noticed that the title "DC's Personal Finance and Stock Investing Blog" has been cut off by the blogger bar.


I am not alone. There are several other PF blogs that have some sort of display issue after having changed to the new Blogger version. A few blogs that I've noticed with significant problems in IE7 are Retiring Early, Growing Money, Money Monk, and Moomin Valley. To these blog owners: if you aren't aware of the problems with your blog, I can Email you a screen capture of what it looks like under IE7.

All new PC computers come with Internet Explorer 7 installed, and about one quarter of my blog readers currently use IE7. This number is should rise in time, as people upgrade their computers and software. So, what should I do? I am considering either modifying the existing template for PFStock, or going to a new one all together. Since I have used the same template since I first started PFStock, it might well be time for an update. I'm looking for a template that looks more modern than this one called "Son of Moto". Does anybody have a suggestion?

One other thing that Blogger Beta changed is the URL for PFStock's RSS feed. The URL is now http://pfstock.blogspot.com/feeds/posts/default. I have had to update a couple of my external RSS readers to point to this new site feed. I hope that my readers were able to update their feeds. Either that, or they might think that I've been on an extended vacation.

PF Stock

Wednesday, May 9, 2007

Obsession Tagged

My blog has been tagged by Moneymonk in this game of obsession tag that is going around the blogosphere. I suppose that it is an invitation for me to list out my obsessions for the world to see...

My obsessions:
1) My wife and family are my first and most important obsession. As it should be, this has been more of a constant in my life, rather than just a temporary obsession. My dear wife, by the way, is often referred to as "my DW" on this blog. I recently remarked to a fellow blogger that my DW prohibits me from publicly disclosing detailed financial information or our net worth on the blog. For the sake of our marriage, this rule has stuck.

2) Gadgets, electronic or otherwise would constitute another main obsession. One example of a gadget I have is the Oregon Scientific wireless weather station that I bought a while ago. It has a radio-controlled (atomic) clock with alarm and electroluminescent backlight, indoor and outdoor (wireless) temperature and humidity sensors, a built-in barometer with altitude adjustment, and a weather trend indicator. Is that gadgety enough for you?

3) That investing and finance are among my obsessions shouldn't surprise my readers. I even started this blog to write about it. Recently, I have been more obsessed with IPOs. Other obsessive topics that I've written about include the brokerage Ameritrade and the online bank NetBank.

4) Tracking readers of my blog could be considered an obsession. Through the site meter I have been tracking my visitors' locations, what they are reading, and oftentimes what they were searching for. Sorry that I recently turned off the site meter statistics for public viewing. As I have grown as a blogger, I now consider these stats to be proprietary information.

5) The last and most recent obsession is trying to determining who started this whole game of obsession tag! As far as I can tell, I have tracked it back to a 20-year old in girl in Malaysia named Jessica whose blog, the Undeniable Beauty, was nominated for an award as the "Most Obnoxious Blogger".

So who is left to tag? I pick Smarty of Growing Money, Frugal of My 1st Million at 33, Kira of Penny Foolish, Blunt Money, and 2million.

PF Stock

Monday, May 7, 2007

Sponsored Post: Payday Loans

Payday lenders fill an important niche that is not served by traditional banks. In an ideal society, everybody would be on top of their finances, and there wouldn't be a need for payday lenders. But reality is not consistent with this utopia, as the majority of us have gotten a little bit behind on bills at some point.

National Payday offers cash advance loans that basically use your next paycheck as collateral. A payday loan is an option to consider if you find yourself in a short-term bind and in need of money. If, for example, your car breaks down or you encounter an unexpected expense, a payday loan could definitely assist you. Obtaining a payday loan is relatively easy. The online application takes only a few minutes to complete. According to National Payday, most no credit check loans are approved within 24 hours.

National Payday's FAQ does a lot to explain the process of applying for a loan. A checking account and a steady job are the main prerequisites to apply. To explain how the loan works, suppose you were to borrow $300 from the payday lender. The lender then transfers this money to your checking account, and expects to be repaid this amount plus a 25% fee ($75 on a $300 loan) when you receive your next paycheck. National Payday currently has a special offer for first time borrowers: you will get your first loan for free, if the full balance is paid by the due date.

I would advise borrowers to read National Payday's disclosure statement before applying for a loan. Understand that, in some cases, the effective annual percentage rate (APR) on the loan can be the equivalent of several hundred percent. Payday loans are designed to help you through a short-term credit need and are not meant for long-term borrowing. If used correctly a payday loan can help tide you over to the next payday.

Saturday, May 5, 2007

Interactive Brokers and the OpenIPO

I've written about buying IPOs as one of my investment strategies. This past week, I was allocated shares in the Interactive Brokers (Nasdaq: IBKR) IPO. Interactive Brokers is an electronic brokerage that allows direct access for trading stocks, options, futures, bonds, and currency instruments (forex) in worldwide markets. Unlike a traditional IPO where the offer price is determined exclusively by the underwriters, this IPO used a Dutch auction to price its shares. The process is known as an OpenIPO. IBKR is underwritten by WR Hambrecht + Co. which developed the OpenIPO process.

The Dutch auction process is a little bit complex to explain. Instead, I am copying the following text from the Interactive Brokers' prospectus:

• Bidders may submit bids through the placement agents or participating dealers.
• Potential investors may bid any price for the shares, including a price above or below the projected price range on the cover of this prospectus.
• Once the auction closes, the placement agents will determine the highest price that will sell all of the shares offered. This is the clearing price and is the maximum price at which the shares will be sold. The clearing price, and therefore the actual offering price, could be higher or lower than the projected price range on the cover of this prospectus.
• We may choose to sell shares at the auction-set clearing price or we may choose to sell the shares at a lower offering price, taking into account additional factors.
• Bidders that submit valid bids at or above the offering price will receive, at a minimum, a prorated amount of shares for which they bid.

In an article posted on MarketWatch, I was able to determine that the "clearing price" described above was $33. The IPO managers then made the decision to price IBKR at $30.01 per share. And yes, there is a difference between $30.01 and $30 per share! I've heard from some people who put in bids at $30, but won't be allocated any shares because they are a penny short. Not surprisingly, the $33 clearing price is approximately the price where IBKR started trading.

For me, I put in an order for 800 shares (at $31 and above) through E*TRADE, but was allocated only 400 shares. My broker's policy is to do a random allocation when there aren't enough shares to go around. Thus, I received the "prorated amount" described above. Now I wonder if any individual got allocated more than 500 shares of IBKR in total.

Regarding Dutch auctions, if we remember back to the Google (Nasdaq: GOOG) IPO in August 2004, the "clearing price" was widely believed to be around $100/share. But the IPO managers for Google made the decision to issue the IPO at $85 -- below the clearing price. This was to guarantee a $15/share pop for Google at the open. The IPO itself priced "below range," so I considered it an uninteresting IPO, at the time. In retrospect, I was very wrong about it.

PF Stock

Thursday, May 3, 2007

PFStock's First Sponsor

I am happy to announce that PFStock has its first official sponsor. The sponsoring site, Thrifty Scot (website: www.thriftyscot.co.uk) contains general money saving and financial advice. The Thrifty Scot is based in the United Kingdom, so understandably, many of its articles focus on financial institutions in Great Britain.

The Thrifty Scot is a good source of information about loans, and consolidating debt to reduce monthly payments. There is also information about mortgages and credit cards. I have personally used the site, and found it to be useful. The Thrifty Scot focuses more on loans and finance, while PFStock also concerns itself with stock investing and trading.

Nevertheless, the site is constantly updated with informative news articles. The Thrifty Scot may be based in Scotland (UK), but it provides a lot of great information that is of international relevance. At the same time, PFStock's growing readership is becoming more international in nature as the number of visitors from overseas have been steadily increasing. PFStock welcomes The Thrifty Scot as a site sponsor.

Tuesday, May 1, 2007

Coutrywide Bank SavingsLink Account

On PFStock, I have posted extensively about my experiences with NetBank. I have found a replacement for the funds that I withdrew from NetBank when I closed my account with them. The winner is ... Countrywide Bank.

Recently, I opened a SavingsLink account at Countrywide Bank. The highlights are that they pay 5.25% APY interest if you have more that $10k, and 5.4% APY if you have over $50k. The interest rate drops to 4.0% APY if your balance is below $10k. The account itself works like an ING or iGo savings account. If you are not familiar with these, the SavingLink account is an online only account that must be linked to a regular savings or checking account that you have at another institution. This is pretty much the only practical way to transfer funds in or out.

Countrywide Bank actually has a branch within walking distance of my home. But unlike most regular banks, the branch doesn't have an ATM and a prominently displayed sign says that they don't have any cash in the branch. When I asked the asked the sole employee of this office how to make a deposit, he showed me a deposit envelope, which was actually a Federal Express envelope. Apparently if you give them a check, they will send by overnight mail to Texas where the deposit is processed. Countrywide did send me a few postage paid deposit envelopes, but I assume that the FedEx method would be faster.

The SavingsLink account doesn't come with either checks or an ATM card. So, most transactions have to go through your linked account. SavingsLink only allows one linked account at a time, and the process of linking an account is cumbersome. Countrywide Bank uses what is known as "trial deposits". When you request that they link an external account to your Countrywide Bank account, they will make two random deposits (of less than $1.00 each) to your external account and ask you to verify the amounts that were deposited. This is to assure that you are actually the owner of the external account, and this process usually takes 2-3 days to complete. One other little hassle is that deposits are subject to a 10 business day hold. This basically means that you won't be able to withdrawal any deposit for a period of two weeks.

In spite of a few hassles to setup a Countrywide SavingsLink account, their interest rates are much better than at NetBank. Indeed, the 5.4% APY rate is better than the vast majority of bank savings accounts available.

PF Stock

Saturday, April 21, 2007

Office Depot Rebates

I have usually had good success with rebate offers for products that I buy. I estimate that I participate in maybe two dozen rebates a year, and have not had any problem 80-90% of the time. However, over the past year, I have sent in three rebates for products that I bought at Office Depot and had a problem receiving each one. If a problem happens with receiving a rebate, I usually consider it a fluke or coincidence. But since a problem happened three times in a row with the same retailer, I think that there a definite problem.

In each case, the rebate got "stuck" in their system. I am still waiting for a rebate on blank DVD media that I bought the day after Thanksgiving. I have talked to their customer service (at Web-Rebates.com), and they said that they would try to expedite the rebate, but it is still in the "Required Validation Period," after almost five months. In any case, Office Depot is now officially off my list of places of where I will shop for rebate items. Curiously, I have not had problems with other retailers who also use "Web-Rebates.com" for rebate submissions. Does anybody else have a similar experience with Office Depot?

On a different note, I will give credit where credit is due. One retailer that I have not had any problem with is the drugstore Rite-Aid. They have a system where you can submit your receipts online instead of by mail. You do have to sign up for an account, and they keep a running total of your combined rebates for the month. Once I've requested a check, I have always gotten my rebate within three weeks of submitting it.

PF Stock

Sunday, April 15, 2007

NetBank Revisited

On the morning of September 20, 2006, I posted here that I was about to begin the process of withdrawing my money from NetBank and close my account with them. In that post, Sayonara NetBank, I referred to this process as "evacuating my money." There and in subsequent posts on PFStock, I cited deteriorating financial conditions at NetBank as one of my prime reasons for closing out my account. Even then, I conceded that NetBank was not likely to be forced into bankruptcy, but in the event that they did declare bankruptcy, it would be a hassle for depositors to get their funds back from the FDIC.

Let's take a look back six months (almost seven months now) at NetBank (Nasdaq: NTBK). On September 20th, the stock closed at $6.10. Today, NTBK trades at a mere $1.74 (a 71% decline). And, NTBK reached an all-time low of $1.48 this past week. This decline is not surprising considering NetBank's deteriorating financials. From NetBank's previous press releases and other information available at their website, we can clearly see a series of quarterly losses over the past year. And early last year, NetBank stopped paying its shareholder dividend saying that they needed "to protect the company's capital base and tangible book value from further erosion."

Then on October 3rd, NetBank announced that it would be replacing its CEO. Even before this event, I had speculated that something fishy was going on at NetBank. A worst-case scenario could be that NetBank customers would need to recover their funds from the FDIC if NetBank becomes insolvent. However, I noted that while this is certainly possible, it is not the most likely case. Nevertheless, I asserted that NetBank could no longer remain competitive with other banks in its market space.

According to a more recent NTBK press release dated February 21, 2007, NetBank recorded a net loss of $202 million or $4.36 per share for 2006. This loss of $4.36 per share over the 12-month period is absolutely staggering when you consider that the entire company is only valued at $1.74 a share. Unfortunately, what is really lacking from NetBank's report is any type of good news. To further exacerbate the already existing problems, NTBK has received a notice from the Nasdaq Stock Market that the company's common stock is subject to delisting. NetBank has been delinquent in its regulatory filings because its former independent auditor resigned as of November 9, 2006. Since then, NTBK has been having difficulty bringing a new auditor on board. Again, this cannot be construed as good news.

For NTBK shareholders, I think that there are better investments out there. Taking a loss may be a difficult thing, but so is watching your remaining investment dwindle to practically nothing.

For NetBank customers, you haven't yet suffered a loss, and you won't due to FDIC insurance. But just the same, there are better banks out there that offer the same FDIC insurance, and significantly higher interest rates.

Further reading:
The Decline and Fall of Internet-only Banks
Unprofitable and Unstable, NetBank Ousts its CEO
More on NetBank

PF Stock

Friday, April 13, 2007

Ameritrade SPAM Again!

I have written about getting SPAM at my Ameritrade Email address before. (See Ameritrade's Unimpressive Site Upgrade.) Toward the end of that post, I described a method where I use a unique Email address for my different bank and investment accounts. This is accomplished through Yahoo's "AddressGuard" feature. If I get spammed at one of these unique addresses, I can delete that Email address and create a new one.

Well, it has happened again! Two days ago, I started receiving spam at both my Ameritrade and Waterhouse Email addresses. The Waterhouse address has never before been compromised. This is now the fourth time that it has happened with Ameritrade! In addition, I have been getting correspondence from other bloggers who are experiencing the same issue. Their Email addresses were compromised as well. And, some are frustrated enough that they will begin moving their money out of Ameritrade as a result. This is a quote from one of the comments that I received:

Today, I have received four "pump 'n' dump" spams at two separate addresses -- one associated with Waterhouse which has been around for several years and another associated with Ameritrade which is only a few weeks old. These are the only two addresses out of the hundreds of vendor email addresses which I've created to be spammed in the last couple of days. If a trojan horse had stolen email addresses from my emailbox, I would have been receiving similar spams at many other addresses as well. The probability that ONLY these two Ameritrade addresses would have been selected for spamming is minute. One two real possibilities exist, in my opinion. 1) The addresses were sold. 2) The addresses were stolen. I believe that #2 is far more likely and worrisome since who knows what other personal data might have been stolen as well. Even more worrisome is the refusal of their "Tech Department" to consider the possibility that they have a problem.


I have received a similar response from TD Ameritrade's customer service people. So, is anybody else in the same boat as us?

PF Stock

Wednesday, April 11, 2007

Money Market Fund Options for TD Ameritrade

The series of posts that I made about my experiences with TD Ameritrade have been very popular at PFStock. Perhaps the most popular of my posts was the one where I exposed Ameritrade's "Hidden" cash sweep account. I have recently come across another cash (money market) option for TD Ameritrade account holders. This is another fund offered through "The Reserve" (website: ther.com).

The fund is called the Reserve Yield Plus Fund Class R (symbol: RYPQX), and is classified by The Reserve as an "enhanced cash fund". Currently, this fund pays in the neighborhood of 5.4% APY. This rate is much better than the default TD Ameritrade cash option which puts you in a sweep account that pays less than 1% interest.

However, unlike the other Reserve funds (offered through Ameritrade's Total Asset Plan) that I've talked about before, this fund is not available as a sweep option which automatically places your uninvested cash into a money market account. Instead it is traded like a No-Transaction Fee (NTF) mutual fund. You would need to put in a mutual fund order each time that you want to buy or sell the fund.

Now I have a few questions for my readers. Has anybody invested in this type of enhanced cash fund before? Do you need to report each mutual fund sale (each time you take money out of the fund) as a broker transaction on Schedule D of your tax return? Presumably, the fund tries to maintain a $1/share valuation, and each transaction would represent $0 in capital gains. And, does anybody know if TD Ameritrade would count each NTF transaction toward qualification for their premier (or APEX) trading status?

I suppose that I would be remiss if I didn't add that The Reserve Yield Plus Fund contains the following disclaimer:
This Fund is not a money market fund. Achievement of the Fund’s objectives cannot be assured. An investment in the Fund is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. Although the Fund seeks to preserve the value of your investment at $1.00 per share, it is possible to lose money by investing in the fund. Yields may vary.

PF Stock

Saturday, April 7, 2007

Dividend Yields

One of my investment strategies is to buy dividend-paying stocks. When making investment decisions on dividend-paying stocks, it is important to know what the dividend yield of the stock is. Basically, a dividend yield is the sum of the regular dividends that a company pays over the course of a year, divided by the current stock price. In the United States, most dividend-paying stocks pay out every three months (quarterly). In a previous post, I stated that Pfizer (NYSE: PFE) had a dividend yield of 3.43%. Currently, Pfizer pays 24 cents per share in quarterly dividends, for a total of 96 cents in dividends per year. At the time of my post, Pfizer was trading at 27.96. If you take the annual dividend divided by the price, you get 0.96/27.96 = 0.0343 or 3.43%.

[Note that PFE has fallen in price to 25.84 and Pfizer recently raised its dividend. The yield is now 1.16/25.84 = 4.49%. It is important to know that when the stock price goes down, the yield goes up. On the other hand, if the stock price went up, the yield would go down.]

When researching a stock at a financial website such as Yahoo Finance, the dividend and yield is listed with the company quote. I estimate that 95% of the time this number is correct. However, sometimes this number is inaccurate or outdated. This can be the case if a dividend has been reduced or eliminated. For example in another post I mentioned that NetBank has sustained a series of quarterly losses, and its management has decided to suspend their dividend. So the yield for NetBank (Nasdaq: NTBK) is actually 0%, but the Yahoo stock information still indicates that it pays a dividend.

Another case is when a one-time special dividend is paid by a company. This will make you believe that the dividend (and thus the yield) is greater than it really is. Unfortunately, it is not always obvious whether a dividend payment is a regular dividend or a special dividend. So be careful when looking only at the dividend yield statistic on financial sites.

While dividend yield is an important criteria used for selecting stocks worth buying, it is not the only criteria. Dividend yield is not the most important criteria either. In future posts, I will cover some of the other criteria that I use for selecting stocks to buy.

This article was originally posted on September 27, 2006. It is being republished today to complement my post about dividends and ex-dividends.

PF Stock

Friday, April 6, 2007

About Dividends and ex-Dividends

One of my investment strategies is to buy companies that pay dividends (i.e. dividend paying stocks). I want to talk about the mechanics of dividends. Basically, stocks could be classified into two categories: those that pay dividends, and those that don't. A lot of smaller, growth companies do not pay a dividend. Companies are not required to pay dividends, and each dividend must be declared by the company (usually at a board of directors meeting) before it is paid.

In the United States, most companies that pay a regular dividend do so every quarter. There are exceptions, however. For example, Eastman Kodak (NYSE: EK) pays its dividend twice a year. When looking at a finance site such as Yahoo Finance, the dividend is listed with the company stock quote. I estimate that 95% of the time this data is correct. However, sometimes it is inaccurate or outdated. For example, a current quote of NetBank (Nasdaq: NTBK) still indicates that it pays a dividend. However, NetBank has sustained a series of quarterly losses, and its management has decided to suspend that dividend early last year. So, its dividend is actually 0.

Typically, when dividends are announced, the company will usually issue a press release that says something like this:

The board of directors of Pfizer Inc today declared a 24-cent fourth-quarter, 2006, dividend on the company's common stock, payable December 5, 2006, to shareholders of record on November 10, 2006.


Let's dissect this statement. For 2006, Pfizer (NYSE: PFE) paid dividends of 24 cents per quarter or 96 cents for the year. The dividend was paid on December 5 to "shareholders of record" on November 10. In order to be a "shareholder of record" one has to own the stock 3 business days before the record date. In this case, that date is November 7. On November 8, the stock goes ex-dividend. What that means is that if you buy the stock on November 8 or later, you are not entitled to this particular 24-cent dividend. The term "ex-" in this case means "without". So as of November 8, the stock trades without the current dividend.

A common question about dividends is "What happens if you sell the stock on November 8 or later, but before the December 5 date when dividends are paid?" In this case, you would be entitled to the dividend, even though you don't own the stock on the pay date. This has happened to me several times where I've received dividends on stock that I no longer own.

PF Stock

Monday, April 2, 2007

Calculating Rate of Return

What rate of return are you earning? For a bank account (savings, money market, or CD), figuring this out is usually pretty straightforward as the bank tells you what the APY and nominal percentage rates are. But what about the annual rate of return on your investments? If you know how much you put in an investment account and when, you can calculate this return using a computer spreadsheet (i.e. Microsoft Excel).

MS Excel has a function called XIRR that calculates the Internal Rate of Return (IRR) of an investment. You must supply the date and amount of each deposit to or withdrawal from the account. Each of these deposits and withdrawals is called a cash flow. Each deposit is considered a negative cash flow, and each withdrawal is considered a positive cash flow.

I was thinking of writing a detailed post about how to calculate your return using the XIRR function in MS Excel. However, I found a very good post that already describes this method in some detail. The blog is Fat Pitch Financials, and the post is here. Look for the link to the file: "Annualized rate of return.xls".

The original blog writer, George, is an actually an economist, so his description is quite involved. By contrast, I'm just a rank amateur on these matters. Nevertheless, I did take six economics/business classes in college, so I will offer you my additional commentary.

First of all, if you are having trouble using the XIRR formula in your spreadsheet, you might need to install what is called the Analysis ToolPak. A symptom of this is if you see "#NAME?" where you use the XIRR formula on your spreadsheet. To add in the Analysis ToolPak (in my version of Excel, at least), go to Tools, Add-ins, and select the Analysis ToolPak. You might need the original Excel (or MS Office) installation disks for this one-time operation.

The other thing that I want to mention is that in addition to the initial value, deposits, and withdrawals, you need to know what the current (or final) value of the account is. Don't forget to include "accrued interest". This is interest that is accrued, but not yet paid to your account. Money market savings accounts usually pay you monthly or quarterly. In the interim between the last time you were paid interest and now, interest accrues, but is not reflected in the balance. You have to estimate the amount of accrued interest, or your results won't be accurate past the last date that interest was paid.

Lastly in the example XL spreadsheet, George includes a line for taxes. Your account value may not include taxes, and you might pay your taxes out of another account. However, in the example, taxes are deemed to be paid out of the investment account. Taxes are, of course, a negative cash flow.

Now you have a general tool that can help you figure your rate of return on investments. In addition to brokerage accounts, this same formula can be applied to CDs, money markets, Prosper.com loans, and just about any other investment that can be valued.

PF Stock

Sunday, March 11, 2007

Blogroll Update

Since my first post about The Blogroll, I have added links to six very good personal finance blogs. Through these link exchanges, traffic to PFStock has increased somewhat. However, I have found that most of my blog traffic comes from repeat visitors, or from people who are searching for specific personal finance and investing topics.

In any case, I am still looking to exchange links with other PF bloggers that write useful, original content. If you have a legitimate personal finance or investing blog, please send me an Email, and I will consider including a link to it here on PFStock. (Note that my Email address is listed on the right side column of my blog.)

Please note that I reserve the right to remove links to any PF blog for any reason. Also, from time to time, I will receive comments to posts on PFStock that are off-topic or contain only advertising links. As a matter of policy, I regularly remove inappropriate comments.

PF Stock

Saturday, March 10, 2007

Crude Oil vs. Cruise Line Stock Prices

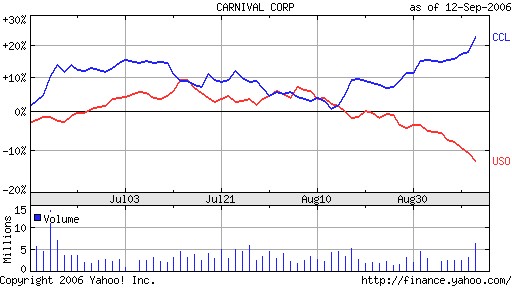
In September 2006, I wrote a post about investing in the cruise line industry. In that post, I asserted that the price of fuel, which is one of the biggest expenses of cruise lines, is a key factor in the price movements of cruise line stocks. I said that there is an inverse relationship between the cost of fuel and the price of cruise line stocks. To review, I have reproduced the graph that I posted of Carnival Corporation (NYSE: CCL), which is represented by the blue line below. The red line is the U.S. Oil Fund ETF (AMEX: USO). USO is an exchange-traded fund that tracks the price of crude oil. Back in September, the price of oil was dropping in price. If you pay attention to what you're paying at the gas pump, then you are attuned to these movements in crude oil prices. As you can see in the graph, the price of oil was dropping, while the price of CCL was soaring.


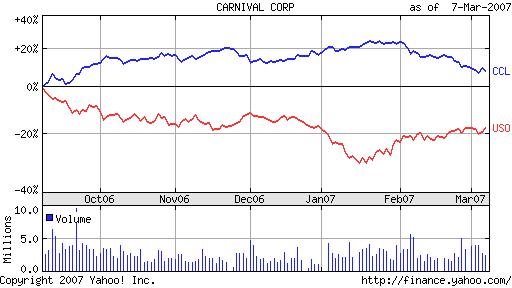
Fast forward six months to today, and you will notice things have changed. I was recently at the gas pump, and noticed that regular gas costs over $3 per gallon for the first time in a while. (Note that I live in Silicon Valley, California.) Below is what that same graph of CCL vs. USO looks like today.


Do you see the inverse relationship? It might be a little hard to see in the chart, but USO reached a low of 42.56 on 1/18/07. Only one day later, on 1/19/07, the price of Carnival Corporation (CCL ) reached a peak of 52.73. Since January, these two charts have reversed course. Oil and gas are increasing in price, while the cruise lines have dropped in price. The North American cruise line industry includes Carnival Corporation, Royal Caribbean (NYSE:RCL), and Norwegian Cruise Lines.

To a lesser extent, the increase in oil prices affects the stock market as a whole as well. So, knowing this relationship is something that you can use to help guide your investments. At this time, I would predict that the cruise lines will drop in value until oil reverses course, or at least until oil prices start to stabilize.

Note: My posts about the cruise line industry are among the most popular posts here at PFStock. Many visitors were searching for information about how to get the shareholder onboard credit benefit offered to cruise line (Carnival Corporation and Royal Caribbean) stock holders. If this is what you are searching for, please read the details in my post about cruise line shareholder benefits for RCCL and Carnival stock holders.

PF Stock

Thursday, March 8, 2007

Daylight Saving Time Reminder

As a reminder, Daylight Saving Time starts this coming Sunday, March 11. I would be interested to know if anyone's VCR automatically adjusts since DST starts early this year.

PF Stock

Wednesday, March 7, 2007

Still Waiting for Windows Vista

A while ago, I had mentioned that I bought a new computer in order to secure a copy of Microsoft Windows Vista. The computer, which I bought back in November 2006, is a Compaq Presario SR2050NX and included the Windows XP MCE 2005 operating system. As part of the deal, I am supposed to receive Microsoft Windows Vista Home Premium from Hewlett-Packard (the parent company of Compaq) after Vista's release. Well, Windows Vista was released back in January. So, where is my free upgrade?

The last time that I checked the status of my Windows Vista order, it said that Vista would be shipped in March 2007. It seems like a while to wait, since I can already go out and buy a new computer with Vista running on it now. On the other hand, compared to the old Dell computer running Windows 98, this new desktop computer is a big improvement. My old computer used to crash on a daily basis.

Is anybody else (who bought a new computer in the last 3-4 months) still waiting for their free Vista upgrade?

PF Stock